 Fixed 14% Profit
The Nadi Card-i Keeps Things Simple With One 14% Rate And No Annual Fee
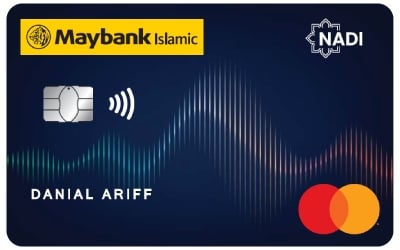
The Maybank Islamic Nadi Mastercard Credit Card-i is a no-frills Islamic credit card. You won't collect TreatsPoints or cashback with it. Instead, you pay a fixed profit rate of 14% per year on any balance you don't pay off. You'll also never pay an annual fee, on the main card or on any supplementary cards.
Maybank Islamic's Ikhwan cards work differently. They charge 15%, 17% or 18% a year, depending on how often you've paid on time in the last 12 months. Miss a few payments and your rate goes up. With the Nadi card-i, the rate stays at 14% a year (1.17% a month), even if you've had a few late months.
So who is it for? It's made for people who sometimes can't clear the whole bill and want to know exactly what that will cost. If you always pay in full, you won't earn any profit anyway, and a rewards card will give you more back.
Pay Your Full Bill Within 20 Days, And You Won't Pay Any Profit
Pay your full statement balance within 20 days of your statement date, and you won't pay any profit on your purchases. Maybank Islamic gives you ibra' (a rebate) that cancels it out.
If you pay only part of the bill, the 14% a year is charged on the purchases you haven't paid for. It's counted from the day each purchase appeared on your account, not from the due date.
The profit isn't compounded, which means you're never charged profit on top of profit. For example, if you have an unpaid RM900 balance, it costs RM10.50 in profit for one month. On another Ikhwan card at the 18% rate, the same RM900 costs RM13.50.
Your minimum payment each month is 5% of what you owe or RM25, whichever is higher. You'll also need to pay any overdue amount, anything above your credit limit and the full monthly amount of any instalment plan or balance transfer plan.
Do note that if you pay only the minimum, profit keeps adding up on the rest. Maybank also uses up to 30% of your minimum payment to cover profit first, so less goes toward what you borrowed.
Withdrawing Cash Costs 14% A Year Plus A 2.52% Fee
You can use the card to withdraw cash, but it's an expensive way to borrow. Each cash withdrawal has a one-time fee of 2.52% of the amount, or RM11.65, whichever is higher. The 14% annual profit starts the same day, with no 20-day break, and runs until you pay it back.
The RM11.65 minimum hurts most on small amounts. Withdraw RM300 and the 2.52% fee is only RM7.56, but you still pay RM11.65. The 2.52% fee only applies above RM11.65, from RM463 upwards. Withdraw RM1,000 and the fee is RM25.20, before any profit.
Your Credit Limit Can Go Up To RM20,000
Your Nadi card-i limit is up to two times your monthly salary, but never more than RM20,000. If you earn RM3,000 a month, you can get up to RM6,000. If you earn RM12,000 a month, you'll still get no more than RM20,000.
Do you already have a Maybank card with a higher limit? That limit won't carry over to this card. If you have two or more Maybank Islamic cards, Maybank gives you one shared limit, and the Nadi card-i's share can't exceed RM20,000.
Carrying debt on another Maybank credit card? You can move it to the Nadi card-i once, up to your approved limit, and pay it off at the lower 14% rate. Only the amount you spent can be moved, not the profit already charged. To do this, call Maybank Group Customer Care at 1-300-88-6688, or +603-7844 3696 if you're overseas. You can't do it through Maybank2u or the MAE app.
Maybank offers a separate balance transfer programme if you want to move your debt from other banks' cards. You can also split big purchases into monthly payments with Maybank's instalment plans, such as EzyPay, EzyPay Plus, EzyCash and Cash Treats. Each one has its own terms.
You Can Pay With Google Pay And Samsung Pay, But Not Apple Pay
You can add the Nadi card-i to Google Pay or Samsung Pay. Apple Pay isn't available yet, and Maybank suggests other cards if you need Apple Pay.
As an Islamic card, you can't use it at shops and services that aren't Shariah-compliant. These include liquor shops, cigar shops, betting and lottery outlets, dating services, and funeral services and crematoriums. If you use the card for anything that isn't Shariah-compliant, you break the card's terms and still have to pay the full amount.
You can also lower your daily tap-to-pay limit or turn tap-to-pay off through Maybank's channels. Do note that Maybank doesn't send SMS alerts when you pay with your PIN at a shop in Malaysia. Turn on notifications in the MAE app so you still get an alert each time.
You'll Need To Earn RM24,000 A Year And Be Aged 21 To 65
To apply for the main card, you need to be Malaysian, aged 21 to 65, and earn at least RM24,000 a year (RM2,000 a month). Supplementary cardholders can be aged 18 to 65.
Keep these documents ready when you want to apply:
- A copy of your NRIC (both sides) or passport, plus one for each supplementary applicant
- Your latest BE form with the official tax receipt
- Your latest three months' payslips
- Your latest six months' savings or current account statements
- If you're self-employed, copies of your business registration and your latest six months' bank statements
Get The Nadi Card-i If You Sometimes Carry A Balance
The Nadi card-i's main benefit is a lower, steadier cost when you can't pay the whole bill. Leave RM3,000 unpaid for a month, and you'll pay RM35 in profit at 14% a year.
On an Ikhwan card at 18%, the same RM3,000 costs RM45. That's RM10 a month back in your pocket, and your rate won't go up if you're late. Do note that RM35 a month still adds up to RM420 over a year if the balance stays the same, so paying it off is always the cheapest option.
If you pay in full every month, a card that earns points or cashback will reward you better. This card also won't suit you if you rely on Apple Pay or need a limit above RM20,000. Before you apply, compare it with other Islamic credit cards on RinggitPlus.