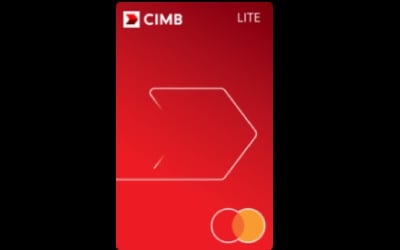
What Is The CIMB Lite-i Credit Card?
CIMB Lite-i is a no-frills Islamic credit card from CIMB Islamic Bank. It launched on 7 October 2026 and does one thing well. It charges a lower, fixed profit rate on any balance you carry over. The rate is 14% p.a. for every cardholder. It doesn't move up or down with your payment record, and the same rate applies to retail purchases and cash advances.
The trade-off is that the card gives you nothing back for spending. There's no cashback, no points and no travel perks. The annual fee is RM0 on the principal and supplementary cards, so the card costs very little to keep. That makes it a card for people who sometimes carry a balance and want to pay less when they do. It isn't for people chasing rewards.
How Does The Fixed 14% Profit Rate Compare With Other Cards?
The easiest way to see what 14% means is to put it next to higher rates. The table below shows the profit on RM5,000 carried for a full year at 14% and at three example rates. The other rows are examples, not named cards. They show how much a few percentage points add up to on the same balance.
| Rate | Profit on RM5,000 for a year | You save with Lite-i |
|---|---|---|
| 18% | RM900 | RM200 |
| 17% | RM850 | RM150 |
| 15% | RM750 | RM50 |
| Lite-i, 14% | RM700 | n/a |
Real bills will differ a little. Profit is worked out on the days each amount is outstanding, so a balance you pay down during the year costs less than the table shows. The saving is largest when you carry a balance for many months, and it's small if you clear the card most months.
When Do You Pay Profit On CIMB Lite-i?
If you pay your full statement balance by the due date, new retail purchases get up to 20 days before any profit starts. Pay less than the full balance and the 14% applies to what's left. As a rough guide, 14% p.a. on a RM3,000 balance comes to about RM35 a month.
Cash advances work differently. There's no grace period, so profit runs from the day the cash is released until you pay it back in full. Cash advances also cost a fee on top (see the fees section below), so they're one of the more expensive ways to use the card.
The minimum payment each month is 5% of your current balance plus service tax, any instalments and unpaid earlier minimums, or RM50, whichever is higher. On a RM3,000 balance, 5% is RM150, so that's the amount that applies. Paying only the minimum keeps your account in good standing, but most of the balance stays on the card and keeps earning profit for CIMB.
How Does The 0% Flexi Pay Plan Work?
From 7 October 2026 to 31 October 2027, CIMB offers a 0% Flexi Pay Plan (FPP-i) for 6 months on a single eligible purchase of RM500 or more. In plain terms, you can turn one larger purchase into six monthly instalments without paying profit on it. A RM1,200 purchase, for example, would come to RM200 a month over the six months.
That suits one-off costs such as a phone repair, a flight or a set of school fees. CIMB decides which purchases qualify and whether other charges apply, so read its FPP-i terms before you buy. CIMB's product page has the current details.
What Does CIMB Lite-i Not Give You?
Lite-i has no cashback, no reward points and no travel or dining perks. You're paying for a low rate, not for rewards, and a card built that way can't also pay you back. If you pay your full balance every month, you'll never use the lower rate, and a card that earns cashback or points will serve you better. Browse our cashback cards or rewards cards if that sounds like you.
What Fees And Charges Come With CIMB Lite-i?
The main fees are listed below. Most are one-off charges you can avoid by paying on time and using the card for purchases.
- Annual fee: RM0 for the principal and supplementary cards. CIMB charges RM25 service tax per card when you activate it and again at each renewal, so you'll still see a small yearly charge.
- Late payment: Up to 1% of the unpaid balance as ta'widh (compensation), with a minimum of RM10 and a maximum of RM100. It doesn't compound.
- Cash advance: 1% of the amount or RM4, whichever is higher, plus 14% profit from day one. You can withdraw up to 30% of your credit limit.
- ATM and card fees: RM2 at PLUS and CIRRUS ATMs, RM20 for a replacement card, RM2 a month for a paper statement and RM10 for an extra statement copy.
- Overseas spending: The Visa or Mastercard exchange rate plus a 1% admin fee and any fee the card scheme adds.
How Much Can You Borrow, And Who Can Apply?
Here's what CIMB asks for and how your limit is set.
- Minimum income: You need to earn at least RM24,000 a year, which is RM2,000 a month.
- Credit limit: It's the lower of RM20,000 or twice your monthly income.
- What that means: If you earn RM2,000 a month, your limit is up to RM4,000. You'd need to earn RM10,000 a month to reach the RM20,000 ceiling.
- No income proof: If you're 21 or older and can't show proof of income, you can pledge a fixed deposit (FD-i) with CIMB equal to the limit you want, up to RM20,000.
- Supplementary cards: You can add them for others, but they draw on your limit.
Is CIMB Lite-i The Right Card For You?
It suits you if you sometimes carry a balance and want a predictable rate without tiers. It also suits you if you'd like a Shariah-compliant card and don't want to pay for rewards you won't use. The 0% Flexi Pay Plan is a useful extra for one big purchase.
Skip it if you clear your balance every month, because a cashback or rewards card will give you more. Compare Lite-i side by side with other cards on RinggitPlus before you apply.
Frequently Asked Questions About CIMB Lite-i
Is a profit rate the same as an interest rate?
For what you pay, it works the same way, so you can compare Lite-i's 14% p.a. directly with the interest rate on a conventional card. The difference is in the structure. Conventional cards lend money and charge interest, while Lite-i follows a Shariah contract called Tawarruq, and CIMB calls the charge a profit rate.
Why does the agreement mention 18%?
CIMB uses 18% as a ceiling when it works out the Bank's Sale Price over five years under the Tawarruq contract. You're charged 14%, and the difference is returned to you through an ibra' (rebate), so 18% isn't what you pay.
Is the 14% rate guaranteed for as long as I hold the card?
Not forever. It's fixed for all Lite-i cardholders now, but CIMB can change rates, fees and the minimum payment with 21 days' notice. Watch for notices from CIMB.
Can a supplementary cardholder spend more than my limit?
No. Supplementary cards share your credit limit, so total spending on all cards can't go past it. You're responsible for everything they charge.
Can I use the card for any purchase?
Not at merchants that aren't Shariah-compliant. The terms say the card must not be used for those, and CIMB can close the card if it is.