






What Is A Cashback Credit Card?
A cashback credit card rewards you with a percentage of eligible purchases, usually credited to your credit card account. Unlike reward points or air miles, cashback gives you a direct monetary rebate based on the card's terms.
For example, a card offering 5% cashback on eligible groceries would earn RM10 on RM200 of qualifying spending, provided the transaction meets the card's conditions and the cashback cap hasn't been reached.
Cashback rates and eligible purchases vary by card. Some reward specific categories, such as petrol or dining, while others offer a lower rate across general retail spending. Minimum monthly spending requirements and cashback caps can also affect how much you receive.
Who Should Get a Cashback Credit Card?
A cashback credit card may suit you if you want to reduce the cost of everyday purchases and prefer cashback over collecting reward points.
It may be a good fit if you:
- Spend regularly on categories rewarded by the card, such as groceries, petrol or dining.
- Prefer cashback credited to your account instead of redeeming points.
- Can meet the minimum spending requirement through your usual purchases.
- Repay your statement balance in full each month to avoid finance charges.
A cashback card may offer less value if you rarely spend in its eligible categories or struggle to meet its minimum spend. If you travel frequently and want to redeem points for flights or hotel stays, compare rewards credit cards as well.
How Cashback Credit Cards Work
Cashback credit cards return a percentage of your eligible spending, but the amount you earn depends on the card’s cashback rate, qualifying transactions, minimum spending requirement and monthly cashback cap.
For example, if your card offers 8% cashback on eligible grocery purchases, spending RM250 could earn you RM20 in cashback. However, you will only receive the full amount if the transaction qualifies and you have not reached the card’s cashback limit.
Four factors determine how much cashback you can earn.
Eligible Transactions and Merchant Category Codes (MCCs)
Banks use Merchant Category Codes (MCCs) to classify merchants according to their primary business activity. These codes help determine whether a transaction qualifies for cashback under a card’s terms and conditions.
This means cashback eligibility often depends on how a merchant is classified, rather than the individual items you buy. For example, groceries purchased at a supermarket may qualify for grocery cashback, while the same items bought at a convenience store may not qualify if the merchant falls under a different MCC.
Common cashback categories include:
| Spending Category | Typical Eligible Merchants |
|---|---|
| Petrol | Eligible petrol stations |
| Groceries | Qualifying supermarkets and hypermarkets |
| Dining | Eligible restaurants, cafés and fast-food outlets |
| Online Shopping | Qualifying e-commerce platforms and online retailers |
| Utilities | Selected electricity, water and telecommunications payments |
| E-Wallets | Eligible reloads or payments, where supported |
Not every transaction qualifies, even if you pay using your credit card. Depending on the card, exclusions may include balance transfers, cash advances, instalment plans, government payments, insurance premiums and quasi-cash transactions.
Some Islamic credit cards may also exclude transactions involving merchants or activities that do not comply with Shariah requirements. Check the card’s terms and conditions for the exact exclusions before applying.
Cashback Rate
The cashback rate is the percentage of eligible spending returned to you. A card advertising up to 10% cashback may offer that rate only for selected categories or when you meet specific conditions.
For example, if you spend RM300 on eligible purchases at a 5% cashback rate, you could earn RM15 before applying any cashback cap or other restrictions.
A higher advertised rate does not always mean higher savings. Compare the rate against your usual spending categories, as well as any minimum spending requirements and monthly limits.
Minimum Monthly Spending Requirement
Some cashback cards require you to reach a minimum amount of eligible retail spending during a statement cycle before you qualify for a higher cashback rate.
For example, a card may offer 8% cashback on selected categories when you spend at least RM2,000 in a statement month. If you spend RM1,900, you may receive a lower base rate instead.
Whether all retail purchases count towards the minimum spend depends on the card’s terms. Some banks include eligible spending across multiple categories, while others apply more specific conditions.
Choose a card whose spending threshold matches your normal expenses. Buying things you do not need just to qualify for a higher cashback rate can cost more than the rewards you earn.
Monthly Cashback Cap
A cashback cap limits the maximum amount you can earn within a specified period, usually a statement month. Once you reach that limit, additional eligible purchases may no longer earn cashback at the advertised rate.
For example, suppose your card offers 10% cashback with a monthly cap of RM30. You would reach the cap after RM300 of qualifying spending, assuming no other conditions apply. Spending another RM200 in the same category would not earn additional cashback under that capped benefit.
Compare the cashback rate and cap together. A card offering 5% cashback with a higher cap may give you more savings than one offering 10% with a lower cap, depending on how much you spend.
Why You May Earn Less Cashback Than Expected
Your actual cashback may be lower than expected if you miss a spending requirement, make purchases that do not qualify or reach the monthly cap.
Before applying, check these conditions:
- Eligible spending categories to confirm that the card rewards the purchases you make most often.
- Minimum monthly spending to see whether your usual expenses qualify you for the advertised rate.
- Cashback caps to estimate the maximum amount you can earn.
- Excluded transactions to identify purchases that do not earn cashback.
- Statement cycle and transaction posting rules to understand which period your purchases count towards.
For example, a purchase made near the end of a statement cycle may only count towards the next cycle if the merchant posts it after the cut-off date. Check your bank’s rules on transaction posting and cashback calculation rather than assuming the purchase date determines when you earn the reward.
The best cashback card is not necessarily the one with the highest advertised rate. Choose one that rewards your regular spending, has manageable conditions and offers a cashback limit that suits your monthly expenses.
How to Choose the Right Cashback Credit Card
The best cashback credit card is one that rewards the categories where you spend the most. Rather than focusing on the highest advertised cashback rate, compare the overall cashback programme, including the eligible spending categories, minimum monthly spending requirement and monthly cashback cap.
Before applying, consider the following:
Your Spending Habits
Review your monthly expenses to identify where you spend the most. If most of your budget goes towards groceries and household essentials, choose a card that rewards supermarket spending. If you drive frequently, a petrol cashback card may offer greater savings. Those who shop online regularly may benefit more from a card that rewards e-commerce transactions.
Your cashback card should complement your existing spending habits, not encourage additional spending simply to earn higher rebates.
Minimum Monthly Income
Every cashback credit card has a minimum income requirement set by the issuing bank. Entry-level cards generally require a lower monthly income, while premium cashback cards often have higher eligibility requirements and may offer higher cashback rates or additional benefits.
Choose a card that matches both your income and your spending patterns rather than applying for a premium card solely because it advertises a higher cashback rate.
Minimum Monthly Spending
Many cashback programmes only offer their highest cashback rates after you reach a minimum spending threshold.
For example, if a card requires RM2,500 in monthly spending but you typically spend RM1,500, you may never qualify for the advertised cashback rate. In this situation, a card with a lower minimum spending requirement could deliver greater savings.
Monthly Cashback Cap
A higher cashback rate does not always translate into higher cashback.
For example, earning 10% cashback with a monthly cap of RM20 means you'll stop earning cashback once you reach the limit. If your monthly spending is relatively high, a card with a lower cashback rate but a higher or uncapped monthly limit may provide better overall value.
Annual Fees and Other Charges
Some cashback credit cards waive the annual fee for life, while others require you to meet a minimum annual spending requirement before the fee is waived.
Compare the annual fee alongside the cashback you expect to earn each year. If the annual fee exceeds your expected cashback, another card may offer better value.
Types Of Cashback Credit Cards
Cashback credit cards reward different types of spending, so the right option depends on where you spend most of your money.
| Cashback Card Type | How It Works | Suitable For |
|---|---|---|
| Petrol Cashback Cards | Offer cashback on eligible fuel purchases, sometimes at selected petrol stations or on weekends. | Drivers who refuel regularly. |
| Grocery Cashback Cards | Reward eligible purchases at participating supermarkets and grocery stores. | Households with regular grocery expenses. |
| Dining Cashback Cards | Offer cashback on eligible restaurant, café and food purchases. | People who frequently dine out or order food. |
| Online Shopping Cashback Cards | Reward eligible purchases made through online retailers or selected e-commerce platforms. | Frequent online shoppers. |
| Utilities Cashback Cards | Offer cashback on eligible utility bills, subject to the bank's payment channel and exclusions. | People who pay recurring household bills by credit card. |
| General Cashback Cards | Provide cashback on a wider range of eligible retail purchases, sometimes at a lower rate than category-specific cards. | People whose spending is spread across different categories. |
Check each card's terms before applying, as cashback eligibility may depend on the merchant category, payment method, minimum monthly spend and cashback cap. A card that rewards your biggest expenses may offer more value than one with a higher rate on spending you rarely make.
Cashback Credit Cards Vs Rewards Credit Cards
Cashback credit cards return a monetary rebate on eligible spending, while rewards credit cards typically let you accumulate points for selected redemptions, such as vouchers, merchandise or travel benefits.
| Feature | Cashback Credit Card | Rewards Credit Card |
|---|---|---|
| Reward type | Cashback credited according to the card's terms. | Points earned on eligible spending. |
| How you use rewards | Receive cashback, usually as a credit or rebate. | Redeem points for available rewards. |
| Main benefit | Straightforward savings on eligible purchases. | Flexibility to redeem points for different rewards. |
| What to check | Cashback rate, monthly cap and spending requirements. | Points earning rate, redemption value and expiry rules. |
| Best suited for | People who prefer direct savings. | People who want to accumulate and redeem points. |
Neither option is automatically better. Compare the value of the rewards against the card's fees, spending conditions and your usual purchases. If you prefer direct savings on everyday expenses, a cashback card may be easier to manage. If you want to redeem points for travel or other rewards, a rewards card may suit you better.
Best Cashback Credit Cards 2026
The best cashback credit card for you depends on your spending habits, the cashback you can earn and the conditions you can comfortably meet.
Compare cards based on the categories you spend on most, such as petrol, groceries and dining. Check the cashback rate alongside the monthly cap and minimum spending requirement, as these determine how much you can earn from your usual purchases.
Before choosing a card, compare:
- Cashback rate to see how much you earn on eligible spending.
- Monthly cashback cap to understand the maximum rebate you can receive.
- Minimum monthly spend to check whether you can qualify using your regular expenses.
- Annual fee and other charges: to account for the cost of keeping the card.
- Eligibility requirements to confirm that you meet the bank's income and application criteria.
The cards below are grouped by spending category to help you compare options based on how you use your credit card.
Best Petrol Cashback Credit Cards in Malaysia
The best petrol cashback credit card depends on where you refuel, how much you spend each month and whether you can meet the card's spending requirements. Some cards reward purchases at a specific petrol brand, while others cover eligible transactions at multiple petrol stations.
Compare the cashback rate, monthly cap and minimum spending requirement before choosing a card.
|
Sarah drives 120km daily for work, plus weekend trips to Ipoh, spending RM900 monthly on Shell petrol. She charges everything to her RHB Shell Visa Credit Card. This includes groceries, online spending, and utilities, hence she can easily hit the RM3,000 minimum. Her petrol spending earns her the RM30 monthly cap, and other categories add another RM30, giving her RM60 total monthly cashback. |
|
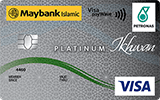
Ali drives to project sites during the week and runs family errands on weekends. He strategically refuels only on Saturdays and Sundays at Petronas, spending RM600 monthly on petrol plus RM200 on Petronas convenience store purchases. The Maybank Islamic Petronas Ikhwan Visa Platinum Card-i gives him 8% weekend cashback with no minimum spend requirement. His RM800 in weekend Petronas spending earns him RM50 monthly (capped), saving RM600 yearly. |
|
Kenneth drives a company car and spends RM2,500 monthly across petrol (RM1,800), Setel app transactions (RM400), and EV charging at Petronas for his wife's car (RM300). The CIMB PETRONAS Visa Platinum-i Credit Card gives him 8% cashback once he hits the RM2,000 minimum spend. His RM2,500 in Petronas-related transactions at 8% would be RM200, but it's capped at RM50 monthly, still RM600 saved per year. |
Best Grocery Cashback Credit Cards in Malaysia
Grocery cashback credit cards help reduce the cost of supermarket shopping, but the best option depends on where you shop and how much you spend each month. Some cards reward selected supermarkets only, while others group groceries with general retail shopping.
Compare the cashback rate, eligible merchants, monthly cap and spending requirements before applying.
| Top Grocery Cashback Credit Cards Malaysia 2026 | |||
|---|---|---|---|
|
|
|
|
|
| Highest cashback rate | Up to 8% bonus cashback on groceries, petrol and selected e-wallets | 10% on eligible online spending, dining, shopping and groceries, and public transport |
10% on eligible petrol, groceries, dining and Grab spending |
| Monthly cap | RM15 per category |
RM10 per month |
RM15 per category |
| Eligible spending | RM2,000 accumulated monthly spend to qualify for 8%. Below RM2,000, the listed rate is 1% on those categories. |
RM1,500 minimum total monthly spend with 0.2% unlimited cashback on subsequent eligible spend after the category cap. |
RM1,500 minimum retail spend per statement month. |
| Eligible cardholder(s) | Principal only | Principal and Supplementary | Principal and Supplementary |
|
Puan Helena spends RM800 monthly on groceries at Giant, RM200 on petrol, and RM1,000 on e-wallet top-ups, totaling RM2,000. The HSBC Amanah MPower Platinum credit card gives her 8% cashback across all three categories once she hits the RM2,000 minimum. Each category caps at RM15, so she earns RM45 monthly (RM15 × 3 categories), saving RM540 yearly. The card only works at Giant, Lotus's, AEON BiG, and Mydin, which suits her since Giant is near her office. |
|
Noah spends RM3,000 monthly on groceries for his weekly Saturday gatherings, plus RM500 on dining out and RM200 on petrol. The AmBank Cash Rebate Visa Platinum Card gives him 10% cashback on groceries with no minimum spend requirement. His RM3,000 grocery spending at 10% would be RM300, but it's capped at RM50 monthly. He also earns cashback on dining (5%, RM25 cap) and petrol (8%, RM20 cap), bringing his total monthly cashback to RM95. |
|
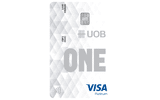
Mrs. Wong and her husband (principal cardholder) spend RM1,600 monthly on groceries across weekly AEON trips. The UOB ONE Card gives them 10% cashback on groceries when they meet the RM1,500 minimum monthly spend. Their RM1,600 grocery spending at 10% gives them RM15 monthly (capped), or RM180 yearly. The card works any day of the week at participating hypermarkets, giving them flexibility on when to shop. |
Best Dining Cashback Credit Cards in Malaysia
Dining cashback credit cards reward eligible purchases at restaurants, cafés and other qualifying food outlets. Some cards offer higher cashback on dining, while others combine dining with groceries, petrol or other everyday spending.
Before choosing a card, check its eligible merchant categories, monthly spending requirement and cashback cap. Food delivery transactions may be treated differently from restaurant payments, depending on the card's terms.
|
Marlina spends RM600 monthly dining out with family and friends, plus RM400 on groceries, RM300 on petrol, and RM200 on Grab rides, totaling RM1,500. The UOB ONE Card gives her 10% cashback across all four categories once she meets the RM1,500 minimum. Each category caps at RM15, so she earns RM60 monthly (RM15 × 4 categories), saving RM720 yearly. The card works any day of the week, not just weekends. |
|
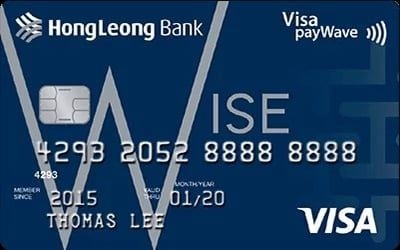
Aziz spends RM1,000 monthly on dining and RM800 on groceries for his weekend cooking sessions, plus RM700 on petrol, totaling RM2,500. The Hong Leong Wise Credit Card gives him 15% cashback once he hits the RM2,500 minimum spend. His combined spending at 15% would be RM375, but it's capped at RM60 monthly. That's RM720 saved per year. The card has an annual fee of RM98, but the cashback more than covers it. |
|
Chong spends RM800 on dining, RM600 on online shopping, RM400 on groceries, RM300 on petrol, and RM200 on utilities, totaling RM2,300 monthly. The Alliance Bank Visa Signature gives him 5% uncapped cashback across all categories. His RM2,300 spending earns him RM115 monthly in cashback, or RM1,380 yearly. The uncapped structure means he never hits a ceiling, making it perfect for his varied spending pattern. |
Best Online Shopping Cashback Credit Cards in Malaysia
Online shopping cashback credit cards reward purchases made through eligible e-commerce platforms and online retailers. Depending on the card, cashback may also apply to selected mobile apps, digital wallets or contactless payments.
If you frequently shop on platforms such as Shopee or Lazada, compare the eligible merchants, spending requirements and cashback cap before applying.
| Top Online Shopping Cashback Credit Cards Malaysia 2026 | |||
|---|---|---|---|
|
|
|
|
|
| Highest cashback rate | Up to 5% bonus cashback on eligible dining, shopping and entertainment |
10% on eligible online spend and 5% on eligible e-wallet top-ups |
Up to 5% cashback on selected contactless purchases at AEON BiG on the 28th of each month |
| Monthly cap | RM30 | RM15 | RM100 |
| Eligible spending | RM5,000 monthly eligible spend for 5%. Lower tiers offer 1% at RM1,000 and 2% at RM2,500. |
RM1,000 minimum retail spend per calendar month. |
Visa payWave at AEON BiG Stores during AEON BiG Thank You Member Day (28th of every month) |
| Eligible cardholder(s) | Principal and Supplementary | Principal and Supplementary | Principal and Supplementary |
|
Ben spends RM2,000 monthly on online shopping (Shopee, Lazada) and RM3,500 on overseas retail during work trips, totaling RM5,500. The HSBC Live+ Credit Card gives him 8% cashback on both local and overseas shopping once he hits the RM5,000 minimum spend. His shopping expenses at 8% would be RM440, but it's capped at RM30 monthly. He also earns 8% on dining and entertainment. Total monthly cashback: RM30, or RM360 yearly from shopping alone. |
|
Farah spends RM1,200 monthly on online shopping across Shopee, Lazada, and Grab orders. The UOB EVOL Card gives her 10% cashback on online spending with a RM1,000 minimum monthly spend. Her RM1,200 at 10% would be RM120, but it's capped at RM15 monthly. She also tops up e-wallets (5% cashback, RM15 cap), bringing her total to RM30 monthly or RM360 yearly. The card has no annual fee for the first year. |
|
Mery spends RM500 monthly at AEON BiG, around RM300 on weekday lunches, and RM200 on weekend grocery stock-ups—all using Visa payWave. The AEON BiG Visa Gold gives her 5% cashback on contactless payments, but only on the 28th of each month (AEON BiG Thank You Member Day). She strategically does her big monthly shop on the 28th, spending RM800 that day at 5% to earn RM40 monthly, or RM480 yearly. |
Best Utility Cashback Credit Cards in Malaysia
Utility cashback credit cards reward recurring household bill payments such as electricity, water, telecommunications and internet services. Some cards require payments to be made through standing instructions or specific payment channels to qualify for cashback.
If you regularly pay household bills with your credit card, compare the eligible utility providers, cashback rate and monthly cashback cap to maximise your savings.
|
Top Utility Cashback Credit Cards Malaysia 2026 |
|||
|---|---|---|---|
|
|
|
CIMB Cash Rebate Platinum MasterCard |
|
| Highest cashback rate | At RM2,500 or more in total monthly retail spend, 5% on eligible petrol, dining, utilities and groceries, and 10% on eligible online dining and grocery spend |
Up to 5% cashback | Up to 5% cashback |
| Monthly cap | RM10 per category | Uncapped | RM30 |
| Eligible spending |
Utility + Petrol + Dining + Grocery |
Utility + Online Shopping + Groceries + Dining + Petrol + Other Retail |
Groceries, petrol, cinema, mobile and utility bill payments. Unlimited 0.2% on eligible online and retail shopping |
| Eligible cardholder(s) | Principal and Supplementary | Principal and Supplementary | Principal and Supplementary |
|
Johari spends RM400 on utilities (TNB, water, Astro), RM800 on groceries, RM600 on petrol, and RM300 on online shopping, totaling RM2,100 monthly. The Alliance Bank Visa Signature gives him 5% uncapped cashback across all categories. His RM2,100 spending earns him RM105 monthly in cashback, or RM1,260 yearly. The uncapped structure means his growing family expenses won't hit a ceiling. He automates his utility payments to never miss the due date. |
|
Paul automates RM300 in utilities (TNB, Astro), RM150 mobile bill, RM100 internet, and RM200 in other bills via Standing Instruction, totaling RM750 monthly. The CIMB Cash Rebate Platinum MasterCard gives him 5% cashback on automated bill payments once he hits the RM3,000 total monthly spend. His RM750 utilities at 5% would be RM37.50, but it's capped at RM30 monthly. He charges another RM2,250 on petrol and groceries to meet the minimum. Annual savings: RM360. |
|
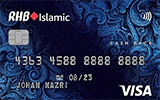
Kamalia and her husband (supplementary cardholder) spend RM250 on utilities, RM600 on petrol, RM800 on groceries, and RM500 on dining, totaling RM2,150 monthly. They need RM2,500 to unlock the 5% tier on the RHB Islamic Cash Back Credit Card-i, so they charge another RM350 on miscellaneous purchases. Each category caps at RM10, giving them RM40 monthly across utilities, petrol, groceries, and dining—RM480 yearly while staying Shariah-compliant. |
How To Maximise Cashback
You can get more value from a cashback credit card by matching its rewards to your regular spending, meeting the qualifying conditions and avoiding finance charges.
Pay Your Credit Card Bill In Full
Pay your statement balance in full by the due date whenever possible. Cashback may not offset the finance charges incurred when you carry an outstanding balance from month to month.
For example, earning RM30 in cashback offers little value if you incur more than RM30 in finance charges on unpaid spending. Treat cashback as a benefit on purchases you can afford, rather than a reason to spend more.
Match The Card To Your Spending
Choose a card that rewards the categories where you spend the most, such as groceries, petrol, dining or online shopping. Review your usual monthly expenses before applying so you can estimate how much cashback you could earn.
A card offering a lower cashback rate on your main spending categories may provide better value than one with a higher rate on purchases you rarely make.
Check The Cashback Cap
Calculate how much eligible spending you need to reach the monthly cashback cap. Once you reach the limit, additional spending may earn a lower rate or no cashback, depending on the card's terms.
If you regularly exceed the cap, compare another card with a higher limit or consider using a second card for a different eligible category. Only do this if you can manage the additional payment dates and repay both balances in full.
Meet Spending Requirements With Planned Purchases
Some cards offer higher cashback only when you reach a minimum monthly spending threshold. Check whether your usual expenses are enough to qualify before applying.
Avoid buying unnecessary items just to unlock a higher rate. If you are close to the threshold, count only purchases you already planned to make and confirm which transactions qualify.
Check Weekend And Merchant Restrictions
Weekend cashback can be useful if you already make eligible purchases on Saturdays and Sundays. However, it may offer less value if your usual spending happens on weekdays.
Check the bank's definition of a weekend, the transaction posting rules and the eligible merchant categories. A purchase made at a restaurant, petrol station or online store does not automatically qualify for the advertised rate.
Frequently Asked Questions (FAQs)
Let's look at the most common questions asked regarding cashback credit cards in Malaysia:
When does weekend cashback actually start and end?
Weekend cashback periods depend on the card's terms and conditions. Some cards define the weekend as Saturday and Sunday, but the exact cut-off time and treatment of transactions may vary by bank.
Check whether cashback eligibility depends on the transaction date, authorisation time or posting date. A purchase made late on Friday or close to midnight on Sunday may not qualify for the weekend rate if it falls outside the bank's stated period.
Before applying, compare the weekend cashback rate with the weekday rate and consider when you normally shop or refuel. A card with a lower rate throughout the week may be more useful if you rarely make purchases during the qualifying weekend period.
When will my cashback appear on my statement?
Cashback appears in one statement cycle after you earn it. If you spend RM2,800 in September and earn RM50 cashback, your October statement (generated around 1st October) shows the September spending, and your November statement shows the RM50 credit.
Do note that transactions are counted by posted date, not transaction date. If you swipe on 28th September but the merchant processes it on 2nd October, that purchase counts toward October's cashback.
Why didn't I get cashback this month?
Common reasons include: You didn't meet the minimum monthly spend, you paid late or paid only the minimum amount, your purchases were in excluded categories (EPP, balance transfers, government payments), you shopped at non-participating merchants, the cashback hasn't posted yet (it appears one cycle later), or you already hit the monthly cap earlier in the month.
Check your statement for a breakdown, or call the bank if you're certain you met all requirements.
Can I combine cashback with the Easy Payment Plan (EPP)?
No. EPP transactions don't qualify for cashback on virtually all Malaysian credit cards. An RM5,000 laptop paid in full might earn you RM50 to RM100 cashback, depending on your card. The same laptop converted to 12-month EPP instalments earns RM0, even though you're charging it to your card.
If cashback matters to you, pay in full. If you need EPP for budgeting, accept that you're trading cashback for payment flexibility. Learn more about Easy Payment Plans.
Does spending by supplementary cardholders count toward the minimum spend?
Yes. All spending by supplementary cardholders is aggregated with the principal cardholder for minimum spend thresholds. If you spend RM1,500 and your spouse spends RM1,200, the bank sees RM2,700 total.
However, cashback caps are also shared. If your card caps dining cashback at RM15 monthly and you've both been eating out, that RM15 gets split across all dining spending by all cardholders; once it's hit, neither of you earns more than that month.
What happens if I pay late or pay only the minimum?
Pay late or pay only the minimum, and you forfeit that month's rebate. Worse, you'll pay 15% to 18% per annum in finance charges on the outstanding balance. Most banks require full payment by the due date to qualify for cashback.
If you earned RM50 in cashback but only paid the minimum on a RM2,000 statement, you lose the RM50 and pay about RM30 monthly in interest charges. Cashback cards only make financial sense if you pay in full every month.
Do I earn cashback on government payments or insurance premiums?
Generally, no. Income tax payments (LHDN), road tax (JPJ), immigration fees, and most insurance premiums are excluded from cashback on nearly all cards. Some banks make exceptions for insurance premiums if the insurer is a partner, but don't assume this. Check your card's terms or test with a small payment first.
Can I use multiple cashback cards to maximise savings?
Yes, but it adds complexity. You could use one card for petrol (12% cashback), another for groceries (8% cashback), and a third for everything else (5% uncapped). This strategy can earn you RM100+ monthly if you spend RM3,000 or more.
The trade-off is tracking multiple statements, due dates, and minimum spend requirements. If managing three cards feels like a part-time job, stick with one versatile card.
Are there cards with uncapped cashback?
A few cards offer uncapped cashback, but they typically require higher minimum spending and offer moderate rates. The Alliance Bank Visa Signature gives uncapped 5% cashback if you spend at least RM2,001 monthly.
Cards with no minimum spend usually offer very low rates (0.2% to 1%) or come with restrictions like weekend-only cashback. There's no card offering 10% uncapped with no minimum spend; banks would lose money.
What happens if I return a purchase for which I earned cashback?
If you return a purchase after receiving cashback, the bank may reverse the cashback associated with that transaction. The adjustment process and timing depend on the card's terms.
For example, if you receive RM25 cashback on an eligible RM500 purchase and later return the item, the bank may deduct the RM25 from your cashback balance or a subsequent statement.
A refund could also affect whether you meet a minimum spending requirement, depending on how the bank calculates qualifying spend. Check your card's terms and cashback entries on your statement if a refund changes the amount you expected to earn.
How does my Debt Service Ratio affect cashback card applications?
Your debt service ratio (DSR) compares your regular debt repayments with your income. Banks may consider your DSR, income, repayment history and existing credit commitments when assessing a credit card application and deciding how much credit to offer.
There is no single DSR threshold that applies to every bank and every credit card application. Each bank uses its own assessment criteria, so a high DSR may affect your chances of approval or the credit limit offered.
For example, if your monthly income is RM5,000 and your existing monthly debt repayments total RM2,000, your DSR is 40% based on those figures.
DSR = (RM2,000÷RM5,000) × 100% = 40%.
This is an illustrative calculation. The income figure and debt commitments used by a bank may differ depending on its assessment method.
Before applying, review your existing repayments and check whether the card's minimum spending requirement fits your budget. You can use the RinggitPlus Debt Service Ratio Calculator to estimate your DSR, but the result does not guarantee approval.
Choose a cashback credit card that matches your spending habits, eligibility and repayment capacity before submitting an application.
How To Apply For A Cashback Credit Card
Check The Eligibility Requirements
Banks set their own eligibility requirements for each credit card. These may include a minimum age, annual income, residency status and supporting documents.
Commonly requested documents include:
- MyKad or another accepted identification document.
- Recent salary slips or other proof of income.
- EPF statements, tax documents or business income records, where required.
Check the bank's official product page for the latest requirements. Meeting the minimum criteria does not guarantee approval, as the bank will also assess your credit profile and existing financial commitments.
Compare Cashback Conditions Before Applying
Look beyond the advertised cashback rate. Compare the eligible spending categories, monthly cap, minimum spending requirement, annual fee and other charges.
A card with a lower advertised rate may offer better value if it rewards your usual purchases and has conditions you can meet without changing your spending habits.
Once you have compared the available options, review the bank's terms and conditions before applying.
Submit Your Application
Once you've selected a cashback credit card, complete your application through RinggitPlus by providing the required personal and income information. The issuing bank will review your application and may request additional documents before making a decision.
Before applying, it's worth checking the latest credit card sign-up offers, as selected cashback credit cards may come with welcome gifts, shopping vouchers or cashback bonuses. If you're still deciding which card best suits your spending habits, you can also use the credit card recommendation service to receive personalised recommendations before submitting your application.