Ryt Bank has extended its savings campaign of up to 4% per annum until 1 February 2027, and its unlimited 1.2% cashback on overseas card spending until 31 December 2026. Both offers were due to end on 30 September 2026, so if you’ve been parking money in Ryt Bank’s Save Pockets, there’s no need to move it just yet.
According to Ryt Bank’s savings account page, your Main Account and Save Pockets earn 2.05% p.a. base interest on the full balance, and Save Pockets get a further 1.95% p.a. bonus interest on the first RM20,000.
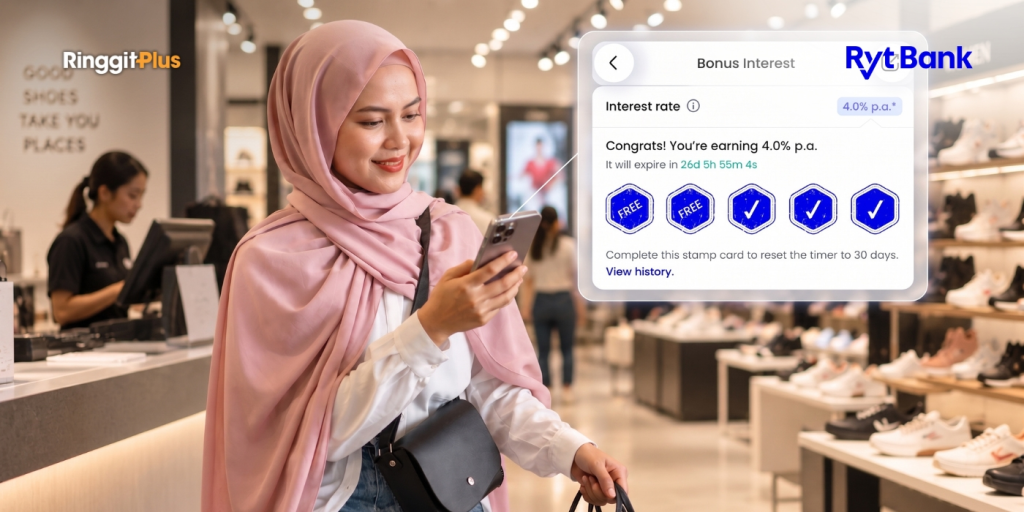
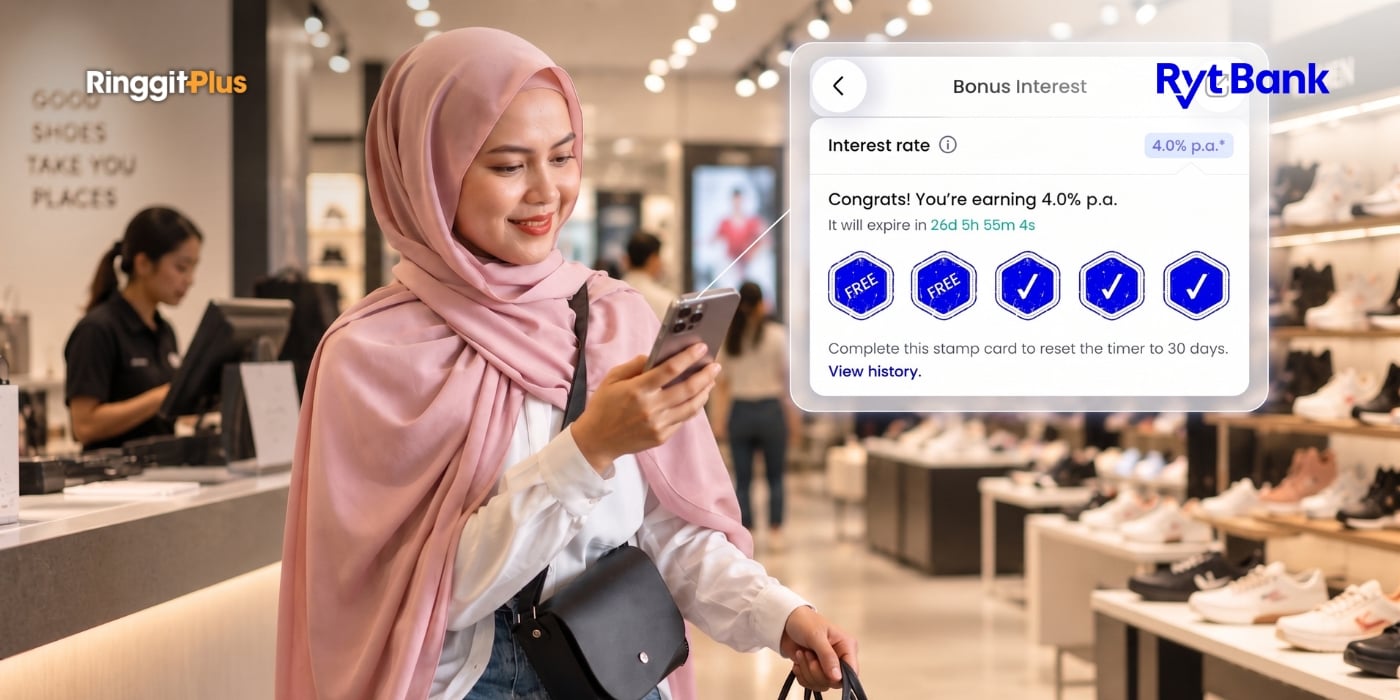
At launch, the split was 3% base and 1% bonus, and you earned the bonus just by keeping money in your Save Pockets. Ryt Bank kept the same split into December 2025 but added the stamp card from 1 December, so the bonus started to depend on how you spend. The base rate then dropped to 2.05% in June 2026, which means nearly half of the 4% now depends on you collecting stamps.
To unlock the bonus, you need five stamps, earned on five different days. You get one stamp a day for spending at least RM10 on your Ryt Card (physical or virtual, local or overseas) or paying a bill of at least RM10 through JomPAY in the Ryt Bank app. Five stamps switch the bonus on for 30 days, and you’ll need another five to keep it going.
If you’re new to Ryt Bank, you get 4% p.a. for your first 30 days after activating your account, without needing any stamps.
Card spending has an exclusion list of merchant categories that don’t count.
The extension adds 124 days of bonus interest, from 1 October 2026 to 1 February 2027. The table below shows what you’d earn over that period.
Save Pocket Balance
Base Interest (2.05% p.a.)
Bonus Interest (1.95% p.a.)
RM10,000
RM69.64
RM66.25
RM20,000
RM139.29
RM132.49
RM50,000
RM348.22
RM132.49
On RM20,000, collecting your stamps until February earns you an extra RM132.49 in bonus interest. To get five stamps every 30 days without changing how you spend, pay your phone and utility bills through JomPAY in the Ryt Bank app. Check that the billers are on Ryt Bank’s list first. You can make up the rest with small Ryt Card payments of at least RM10 on other days. Anything above RM20,000 earns the 2.05% base rate only, so a RM50,000 balance earns 2.83% p.a. overall while the bonus runs.
Do note that the bonus is subject to an overall deposit cap across all customers, allocated on a first-come, first-served basis, and Ryt Bank can change the rates or end the campaign early with notice. Deposits are protected by PIDM up to RM250,000 per depositor.
Spending Abroad With The Ryt Card Now Costs 2% In Fees
The 1.2% cashback applies to in-store purchases made outside Malaysia with the physical Ryt Card, with no cap on how much you can earn. Online and phone payments don’t qualify, in any currency. E-wallet top-ups, gift cards, cryptocurrency and gambling don’t qualify either. Cashback goes into your Ryt Pocket and can take up to 14 business days to appear.
Ryt Bank waived its foreign transaction fee from launch until 31 July 2026. Its fees and limits page (updated August 2026) and the Ryt Card product disclosure sheet (July 2026) now list a fee of 2% on foreign currency transactions, with Visa’s exchange rate on top.
If you spend RM1,000 at a shopping mall in Bangkok during the year-end school holidays, you’ll pay RM20 in fees and get RM12 back, so you lose RM8, plus whatever Visa’s exchange rate costs you. If you don’t already have the physical card, it also costs RM12 to issue.
Saving Until February And Spending Abroad
The savings extension suits you if you keep up to RM20,000 as an emergency fund and don’t mind collecting stamps every month. If you’d rather not track stamps, or your savings are well above RM20,000, compare the rate against other options on our savings account comparison page. If you’re travelling before the year ends, compare the Ryt Card against the other options on our multi-currency debit card page before you decide which card to bring.
Follow us on our official WhatsApp channel for the latest money tips and updates.
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister’s cats.
00votes
Article Rating
SHARE
About THE AUTHOR
Christina Chandra
Christina Chandra
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister's cats.

Comments (0)