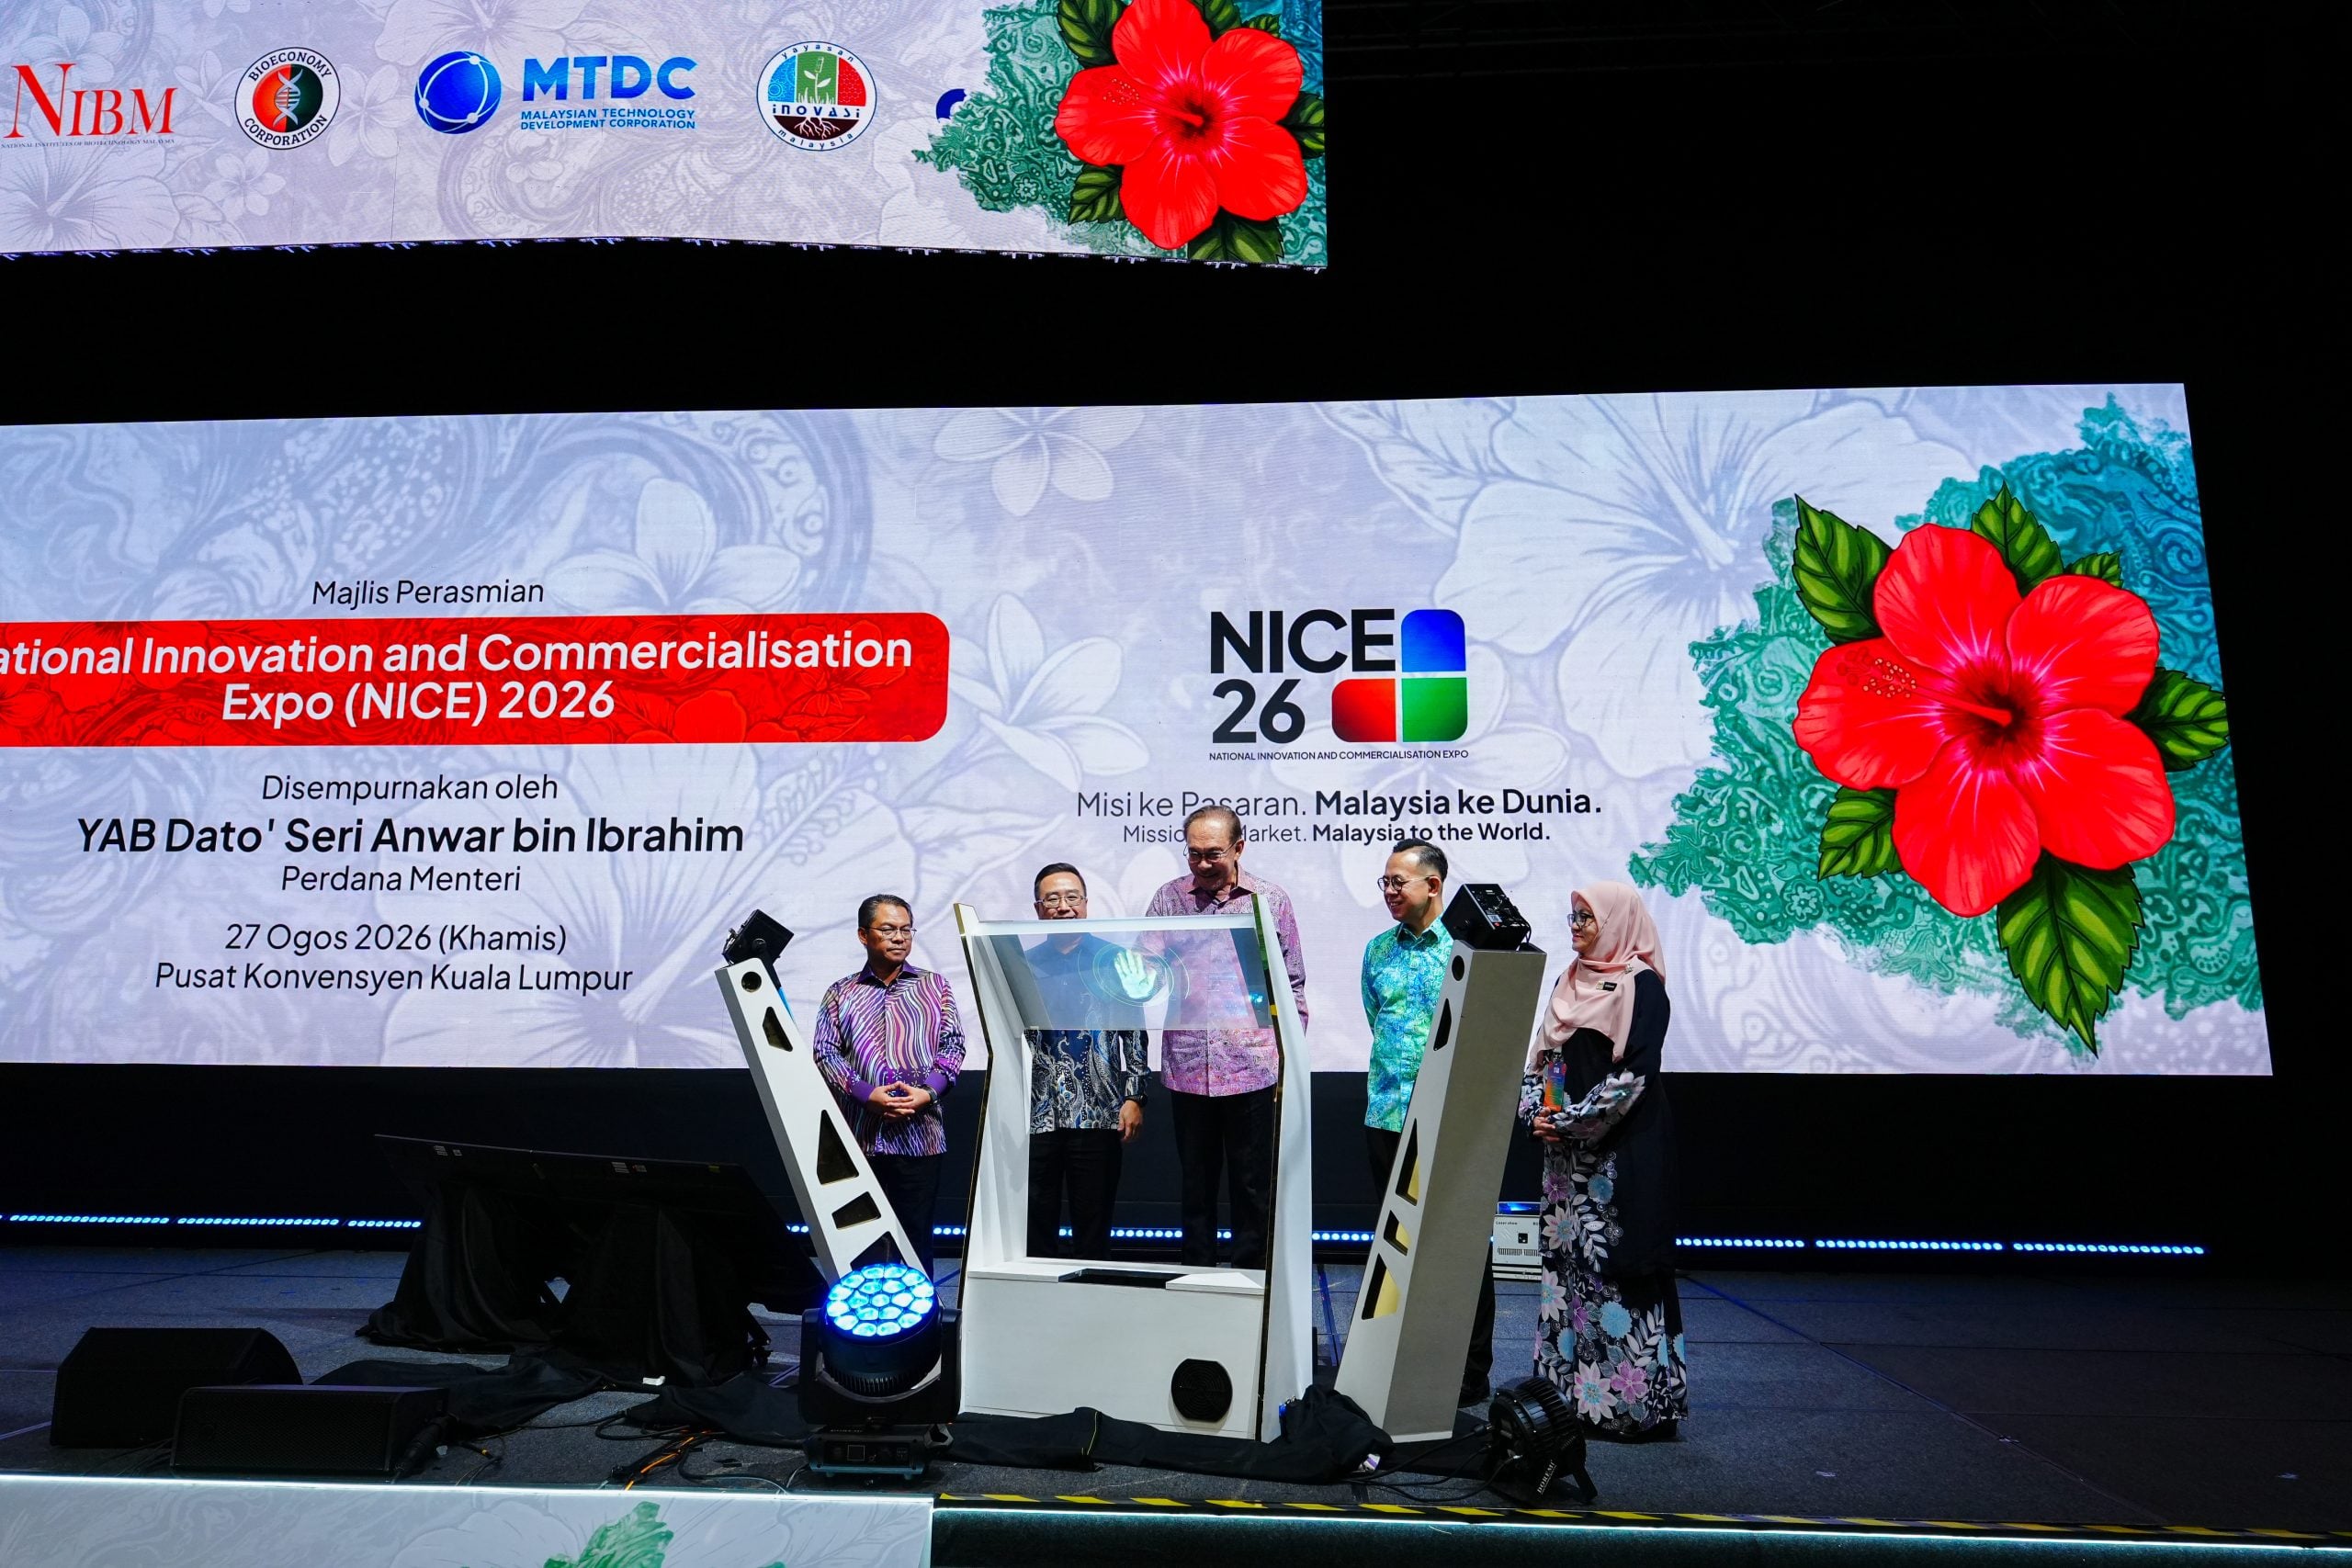
We were at Sasana Kijang in Kuala Lumpur on 25 September 2026, where Bank Negara Malaysia (BNM) held a media briefing on MediAsas. The base-level medical plan is backed by BNM, the Ministry of Health (MOH) and the Ministry of Finance (MOF), and BNM described it as a bridge between public and private healthcare. MediAsas has been in pilot since July 2026 and opens to the public in January 2027.
Only about 22% of the population has medical and health insurance or takaful (MHIT) coverage, according to BNM. Patients pay 39% of the country’s healthcare spending themselves, while private insurance covers 8%. In private hospitals, insurers and other payers cover most of the bill. Even so, patients paid RM932 million of the RM4.88 billion in bills ProtectHealth Corporation had collected as of 9 September 2026, or roughly RM1 in every RM5. If you don’t have a medical card, a private hospital bill comes straight out of your savings.
MediAsas Is A Medical Card With Standard Rules
The first thing BNM wanted us to understand is that MediAsas isn’t a national insurance scheme. It’s voluntary, and you buy it from an insurer or takaful operator like any other medical card. It’s a standalone plan with no investment element, and it’s fully underwritten, so your health is assessed when you apply.
The benefits, pricing approach, underwriting requirements and claims process are standardised across every participating insurer and takaful operator, so you get the same cover whichever company you buy from. Every plan covers you up to age 85, has no lifetime limit and comes with guaranteed renewal.
Hospital stays, based on shared-room rates (you pay the difference if you want a private room)
Treatment before and after a hospital stay, including GP visits, physiotherapy, and home nursing care
Daycare procedures such as endoscopy
Outpatient treatment at a hospital for dengue, influenza, bronchitis and pneumonia, up to RM3,000 a year
Cancer treatment and drugs on an approved list
BNM said that from 2027, you’ll also be able to use your EPF Akaun Sejahtera savings for MediAsas through i-Lindung, an option that was still under discussion in January 2026.
Teras Or Fleksi Depends On The Cover You Already Have
There are two MediAsas plans, and the main difference is the deductible, which is the part of the bill you pay before the plan pays the rest. MediAsas Teras is the base plan, aimed at people who don’t have any cover or are at risk of letting their current plan lapse. MediAsas Fleksi is for working adults who already have employer medical cover or enough savings to handle smaller bills, and want protection against a very large one.
Your share of the bill also depends on where you’re treated. It’s lower at a MediAsas panel hospital, which is a private hospital on the official MediAsas list.
MediAsas Teras
MediAsas Fleksi
Annual limit
RM100,000 (below 60), RM150,000 (60 and above)
RM300,000
Deductible at MediAsas panel hospitals
RM500 per disability (below 60), RM1,000 per disability (60 and above)
RM10,000 a year
Deductible at other hospitals
Same as MediAsas panel hospitals, plus 20% of the bill, up to RM3,000
RM15,000 a year
Outpatient cover for dengue, flu, bronchitis and pneumonia
Up to RM3,000 a year, with an RM50 deductible per visit
Up to RM3,000 a year, after the yearly deductible
With Teras, a disability means one illness or injury, including any complications from it. Treatment within 90 days of leaving hospital counts as the same episode.
In the example BNM walked us through, a GP visit, a hospital stay, a follow-up and a second stay for complications came to RM40,700. It all counted as one episode, so the policyholder paid RM500 and MediAsas paid RM40,200.
With Fleksi, the deductible is counted across the policy year, and your employee benefits can pay it. If your employer’s cover pays the first RM10,000 of a bill, Fleksi pays the rest, up to RM300,000. The same yearly deductible applies to Fleksi’s outpatient cover, so a flu visit won’t be covered unless you’ve already met the RM10,000 deductible that year.
Without other cover, you’d pay most hospital bills in full under Fleksi. Insurance Services Malaysia data for 2024 shows half of all claims came to RM5,695 or less, and three in four came to RM10,069 or less. On a RM5,695 bill at a MediAsas panel hospital, a Teras holder under 60 pays RM500 and the plan pays RM5,195. A Fleksi holder with no employer cover pays the whole RM5,695. If you don’t have any medical cover now, Teras is the plan to look at first.
Is RM100,000 A Year Enough?
The RM100,000 Teras limit was set using claims data. In 2024, only one claim in 100 went above RM55,225. The limit will be reviewed every year.
If you need more cover, BNM suggested three options. You could pair Fleksi with your employer benefits or savings, keep or buy a higher-limit plan from an insurer or takaful operator, or add a MediAsas top-up for specific conditions, which insurers will offer separately.
More People With Existing Conditions Can Get Covered
Many people with an existing condition can’t get a medical card at all today. MediAsas is designed to accept people whose condition is stable and well-managed.
Early-stage cancers in remission, such as breast, colorectal, prostate, and cervical cancer, priced like any other applicant once remission conditions are met
Single-vessel coronary heart disease, under MediAsas Fleksi only and with an extra premium
Mental health and developmental conditions, such as mild narcolepsy and stress disorders
Mild and moderate autism
Getting accepted isn’t the same as being covered for that condition. When you apply, the insurer may cover the condition, cover it only after a waiting period, charge you an extra premium (known as loading) or exclude treatment for it altogether. BNM’s FAQ lists existing conditions as a standard exclusion, so expect treatment for your existing condition to be left out, even if a new illness is covered.
After Seven Years, Most Undeclared Conditions Can’t Be Used Against You
Non-disclosure is when you don’t mention a condition you had when you applied. Today, an insurer can investigate and turn down a claim for suspected non-disclosure at any point in the life of your policy. MediAsas limits this with what it calls a no look-back provision.
After seven years of continuous cover, your insurer can only investigate if it suspects the non-disclosure was deliberate, reckless or fraudulent, or if the claim involves one of five serious and progressive conditions.
Cancers
End-stage organ failure and transplant-related conditions
Major heart and blood vessel conditions
Major neurological disorders
Systemic autoimmune and inflammatory disorders
Even then, if the condition you didn’t declare has nothing to do with your claim, the claim can’t be withheld. The simplest way to stay clear of all this is to declare everything when you apply, including conditions you think are minor.
Indicative Premiums Range From RM60 To RM550 A Month
Pricing wasn’t shared at the briefing. In July, MOF put indicative premiums at around RM60 to RM550 a month for people joining up to age 70. Final premiums will be set before the January 2027 launch.
MediAsas premiums will be reviewed every year. Because risk is shared across all participating insurers, BNM said increases should be smaller and steadier than the sharp jumps many medical cards see every three or five years.
DRG Changes How Your Hospital Gets Paid
The final session was led by ProtectHealth Corporation CEO Wan Mohd Hazwan Wan Mohd Najib and Dr Yap Wei Aun, Chief Executive Officer of MOH’s Health Transformation Office. Hospitals today charge you for every item on your bill. Under diagnosis-related groups (DRG), a new way of paying hospitals, treatment is grouped by diagnosis, procedure and severity, and the hospital is paid one fixed amount for the whole stay.
The speakers showed us how this works with Aiman, a 38-year-old admitted for food poisoning. Under today’s system, his three-night stay comes to RM12,000. Under DRG, his case is graded moderate, and the hospital receives a single rate of RM10,000 for the stay.
For you as a patient, your policy terms, deductible and annual limit stay the same. Wan Mohd Hazwan said DRG should make your bill clearer and more predictable, and that decisions about your care stay with your doctor. The DRG rate also doesn’t limit what your insurer can approve in a guarantee letter (GL), the letter your insurer sends the hospital to confirm it will pay. If your stay gets complicated, your cover isn’t cut off at the DRG rate.
Don’t Cancel Your Medical Card Just Yet
MediAsas matters most for two groups of people. If you don’t have any medical cover, MediAsas gives you a simpler way in from January 2027. If an existing condition has stopped you getting a medical card until now, it may be your first real chance at cover. Once you sign up, nothing is covered in your first 30 days except accidents, and treatment for specified illnesses has a 120-day waiting period.
If you already have a medical card, keep it. Dropping your plan now could leave you without cover before launch. Once final premiums are out, compare medical cards on RinggitPlus, including deductible medical cards, against MediAsas before you decide.
If your premium has gone up recently, read how insurers and takaful operators committed to staggering premium adjustments. If you’re new to all this, start with what a medical card is and how to get one. We’ll update you when they’re confirmed.
Follow us on our official WhatsApp channel for the latest money tips and updates.
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister’s cats.
00votes
Article Rating
SHARE
About THE AUTHOR
Christina Chandra
Christina Chandra
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister's cats.

Comments (0)