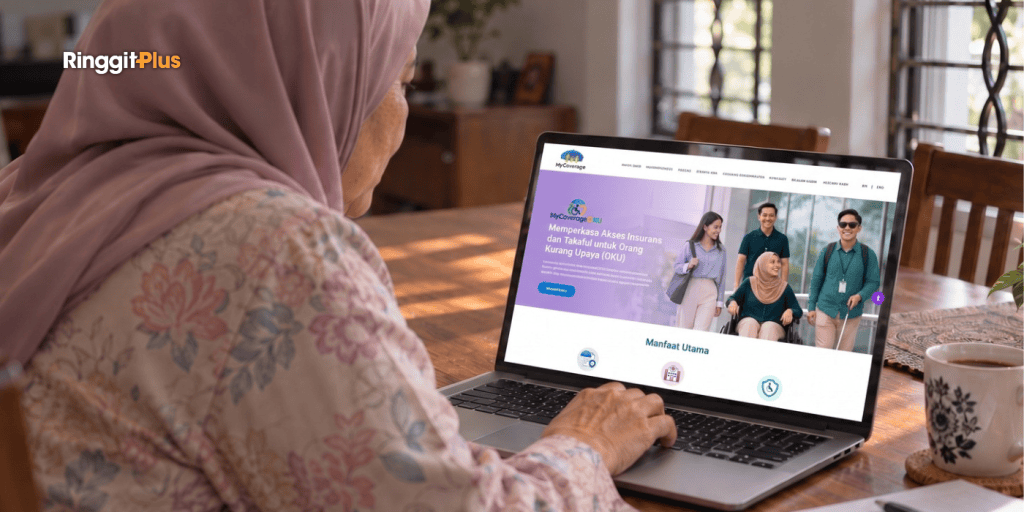
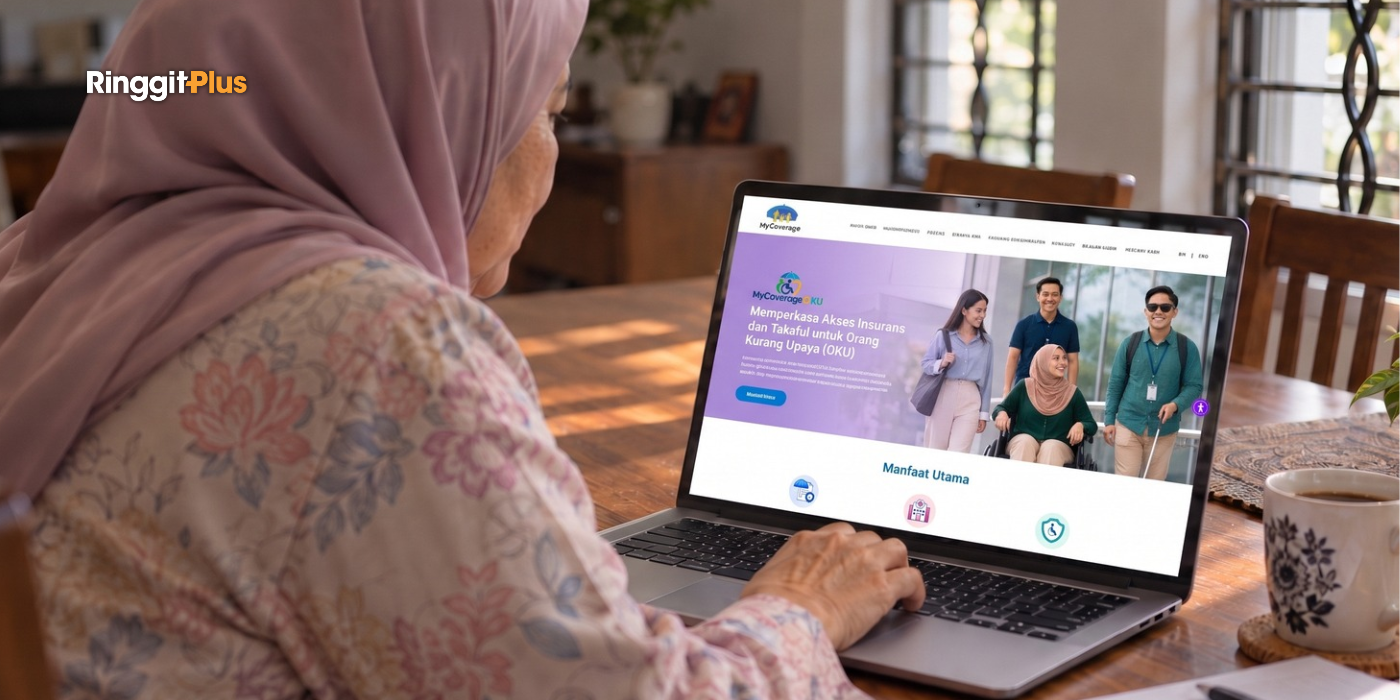
Bank Negara Malaysia (BNM) has launched MyCoverageOKU, a website that lists insurance and takaful plans persons with disabilities (OKU) can apply for. BNM developed it with the Financial Education Network and insurance and takaful companies. It is for OKU, and for parents or caregivers looking for cover for someone else.
MyCoverageOKU lists 107 plans from 23 insurance and takaful brands, including Allianz, Etiqa, FWD, and Great Eastern. Not every plan on MyCoverageOKU is made only for OKU. It also lists everyday plans that anyone can apply for, such as car insurance, home insurance, and savings plans. Below, we show you how to search the list and what to ask before you buy.
Searching The MyCoverageOKU Product List
The site opens in Malay, so tap ENG at the top of the page to switch to English. The site lets you make the text bigger and turn on high contrast.
Scroll down to the Insurance and Takaful Product List. Product type lets you pick life insurance, family takaful, general insurance, or general takaful. Life insurance and family takaful mostly pay out on death, illness, or disability. General insurance and general takaful mostly cover accidents, cars, and homes. Plans that pay hospital bills can come under either kind. Product category sorts plans by what they pay for, such as accidents, hospital stays, or cancer. The underwriting filter shows plans that check your health before accepting you, or plans that don’t.
The Four Details On Each Plan
Open any plan and you’ll see a card with the same four details. Prices aren’t on the site, so you’ll need to ask the provider for a quote.
On The Card
What It Means
Benefits
What the plan pays for, such as death, hospital allowance, or medical bills
Underwriting (Yes or No)
Yes means the provider checks your health before it accepts you
Documents
What you need to apply, such as your OKU card or a doctor’s letter
Contact
The provider’s phone number and email
Of the 107 plans, 50 don’t need underwriting, so you won’t face a health check to get them. That makes them easier to get. Plans without a health check can pay less or leave out more, so read the benefits on each card closely.
Accident Cover Isn’t Medical Cover
Of the 107 plans, 25 are personal accident (PA) plans. A PA plan pays out when an injury, disability, or death is caused by an accident. It won’t pay your hospital bill if you fall sick.
For example, GREAT Tenang, a PA plan from Great Eastern, costs RM54 a year, which works out to RM4.50 a month. If you die or become totally and permanently disabled in an accident, it pays RM42,500. It also pays RM50 a day for a hospital stay, for up to 30 days. Its product disclosure sheet (PDS) is a short summary of the plan. It lists what the plan won’t cover, including conditions you already have and mental disability. The plan also leaves out people who are bedridden, in a coma, or have both a vision and a hearing disability. The plan is for ages 7 to 70.
The Medical & Hospital filter shows 16 plans. Four of the 16 plans pay hospital and surgical bills, and all four need underwriting. The rest are mostly accident, travel, or hospital allowance plans. If none of the four suits you, you can compare medical cards from other insurers and takaful operators on RinggitPlus.
MediAsas is a basic medical plan from BNM, the Ministry of Health and the Ministry of Finance. It opens to the public in January 2027. Insurers and takaful operators sell it. It checks your health when you apply, and conditions you already have are a standard exclusion. Ask whether it would pay for treatment linked to your disability.
Check That Your Disability Is Covered
Plans built for OKU don’t cover every disability. Etiqa’s i-Care OKU is for people aged 17 to 69 with visual, hearing, speech, or physical disabilities. If you have two disabilities, one must be physical and the other visual, hearing, or speech. FWD SpecialMed 2 accepts people with autism, ADHD, and Down syndrome, as well as visual and hearing disabilities.
Check the documents section too. i-Care OKU needs an OKU card from the Social Welfare Department (JKM). Some plans, including ones from Allianz, Chubb, Generali, and FWD, will take a letter or statement from your doctor instead.
Questions To Ask The Provider
MyCoverageOKU doesn’t sell plans. You buy from the insurer or takaful operator, using the contact details on the card. Have your IC and OKU card or doctor’s letter with you when you call, and ask these questions.
How much does the plan cost at my age?
Is my type of disability covered or excluded?
Does it pay for illness, or only for accidents?
Are conditions I already have excluded?
Can I have a copy of the PDS to read first?
Ask about the free-look period as well, which is the time you have to cancel and get your money back. GREAT Tenang refunds your premium if you cancel within 15 days of getting the policy and haven’t made a claim.
If you think a provider has treated you unfairly, complain to its complaints unit first. If it doesn’t reply within 14 days, you can refer the complaint to BNM through BNMLINK. If your claim is rejected or you’re unhappy with the provider’s decision, the Financial Markets Ombudsman Service (FMOS) can look at it. It’s free, and it handles disputes up to RM250,000. You have six months from the provider’s final decision to go to FMOS.
Before you pay for any plan, put two or three PDS documents side by side. Compare what each one leaves out, as well as the price. A low premium won’t help you if the plan excludes your disability.
Follow us on our official WhatsApp channel for the latest money tips and updates.
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister’s cats.
00votes
Article Rating
SHARE
About THE AUTHOR
Christina Chandra
Christina Chandra
Christina writes about personal finance with an eye for making the complicated feel straightforward. She is drawn to the everyday money decisions people face and genuinely enjoys finding the clearest way to explain them. Between articles, she is probably napping, on a hiking trail, or terrorising her sister's cats.
We provide weekly updates on every Friday at 5pm on the prices of RON95, RON97 and Diesel in Malaysia and a chart that shows the movement of fuel prices across a 6-week period. Bookmark this page now!

Comments (0)